Selling Your Home After 55: Could Renting Be the Key to Greater Financial Freedom?
For many adults over 55, selling a longtime home is about much more than moving. It raises an important question:
If I sell my home and begin renting, will my money last—and will my future housing costs remain manageable?
There is no single answer that is right for everyone. Homeownership can build wealth and provide stability, while renting can offer simplicity, flexibility, and freedom from many of the responsibilities that come with maintaining a home. The right decision begins with understanding the complete financial picture—not simply comparing a mortgage payment with monthly rent.
Housing remains a major retirement expense
Even after a mortgage is paid off, owning a home is never truly free. Property taxes, homeowners insurance, association fees, maintenance, repairs, landscaping, pest control, and major replacements can continue for as long as you own the property.
Housing is also one of the largest categories in a household budget. The U.S. Bureau of Labor Statistics tracks housing expenditures as part of its annual Consumer Expenditure Survey and provides specific spending data based on age and other household characteristics. Its data reinforces the importance of accounting for housing when planning for retirement. Review the latest Consumer Expenditure Survey tables from the U.S. Bureau of Labor Statistics .
The question, therefore, is not simply:
“Would my rent be more or less than my mortgage?”
A more useful question is:
“What does it truly cost me each year to own, insure, maintain, repair, and operate my home—and how predictable are those expenses?”
Homeownership has benefits—but it also carries responsibilities
Homeownership can be a valuable source of financial security. The equity accumulated in a home may represent a significant portion of an older adult’s total wealth.
However, the Harvard Joint Center for Housing Studies also recognizes the challenges associated with homeownership, particularly the cost and responsibility of maintenance. Its Housing America’s Older Adults 2023 report notes that some older adults choose multifamily housing for on-site amenities, cost savings, accessibility, and reduced responsibility for repairs and maintenance.
The same report found that more than 7 million older households rent, representing more than one in five households headed by an older adult. It also reported that approximately 4 million households live in age-restricted housing for adults 55 and older—and about 60% of those households are renters. Read Housing America’s Older Adults 2023 from Harvard’s Joint Center for Housing Studies.
Renting after 55 is not necessarily taking a step backward. For the right person, it can be a deliberate lifestyle and financial decision.
Selling can convert home equity into greater flexibility
Selling a home may release equity that can be used for retirement savings, income planning, travel, healthcare needs, family goals, or an emergency reserve.
That does not mean the proceeds should be spent or invested without a plan. The U.S. Securities and Exchange Commission’s Investor.gov advises people receiving a substantial lump sum to evaluate their full financial situation, identify their goals, avoid rushed decisions, and carefully investigate any financial professional or investment opportunity. Read the SEC’s guidance on making decisions about a lump-sum payment.
Before selling, it may be helpful to meet with a qualified financial or tax professional to consider:
Expected net proceeds after selling costs
Capital-gains tax considerations
Current and future monthly income
Healthcare and long-term-care needs
Emergency savings
The effect of inflation
Expected rent and other community fees
How the remaining proceeds will be saved or invested
Selling a home and renting can create financial flexibility—but only when the decision is supported by a realistic long-term plan.
Predictability may be as valuable as a lower payment
One of the greatest concerns in retirement is not always the amount of an expense. Sometimes it is the uncertainty surrounding it.
A homeowner may go several months without a major expense and then suddenly face a roof replacement, air-conditioning failure, plumbing problem, storm-related repair, or insurance increase. These expenses can be difficult to absorb on a fixed or changing retirement income.
Renters generally trade many of those unpredictable ownership expenses for a defined monthly payment. Rent can increase, so prospective residents should carefully review the lease, renewal terms, additional fees, included services, and responsibility for utilities and repairs.
The Consumer Financial Protection Bureau offers resources designed to help older adults make informed decisions involving debt, retirement funds, home equity, and financial security later in life. Explore the CFPB’s financial-security resources for older adults.
The value of renting extends beyond the numbers
The financial comparison matters, but so does quality of life.
A maintenance-free or maintenance-reduced rental lifestyle may provide:
Less time spent arranging repairs and overseeing contractors
Freedom from lawn and exterior-property maintenance
Fewer hurricane-preparation and storm-recovery responsibilities
A more manageable, accessible home
Greater flexibility if personal circumstances change
Convenient access to amenities, activities, and social opportunities
More time for travel, family, hobbies, and friendships
The Harvard report also emphasizes the growing demand for accessible housing. It found that 55% of adults age 80 and older report at least one disability and identifies single-floor living as an increasingly important feature as the population ages.
Choosing a home that is manageable today—and remains practical in the years ahead—can be an important part of planning well.
A different way to think about renting
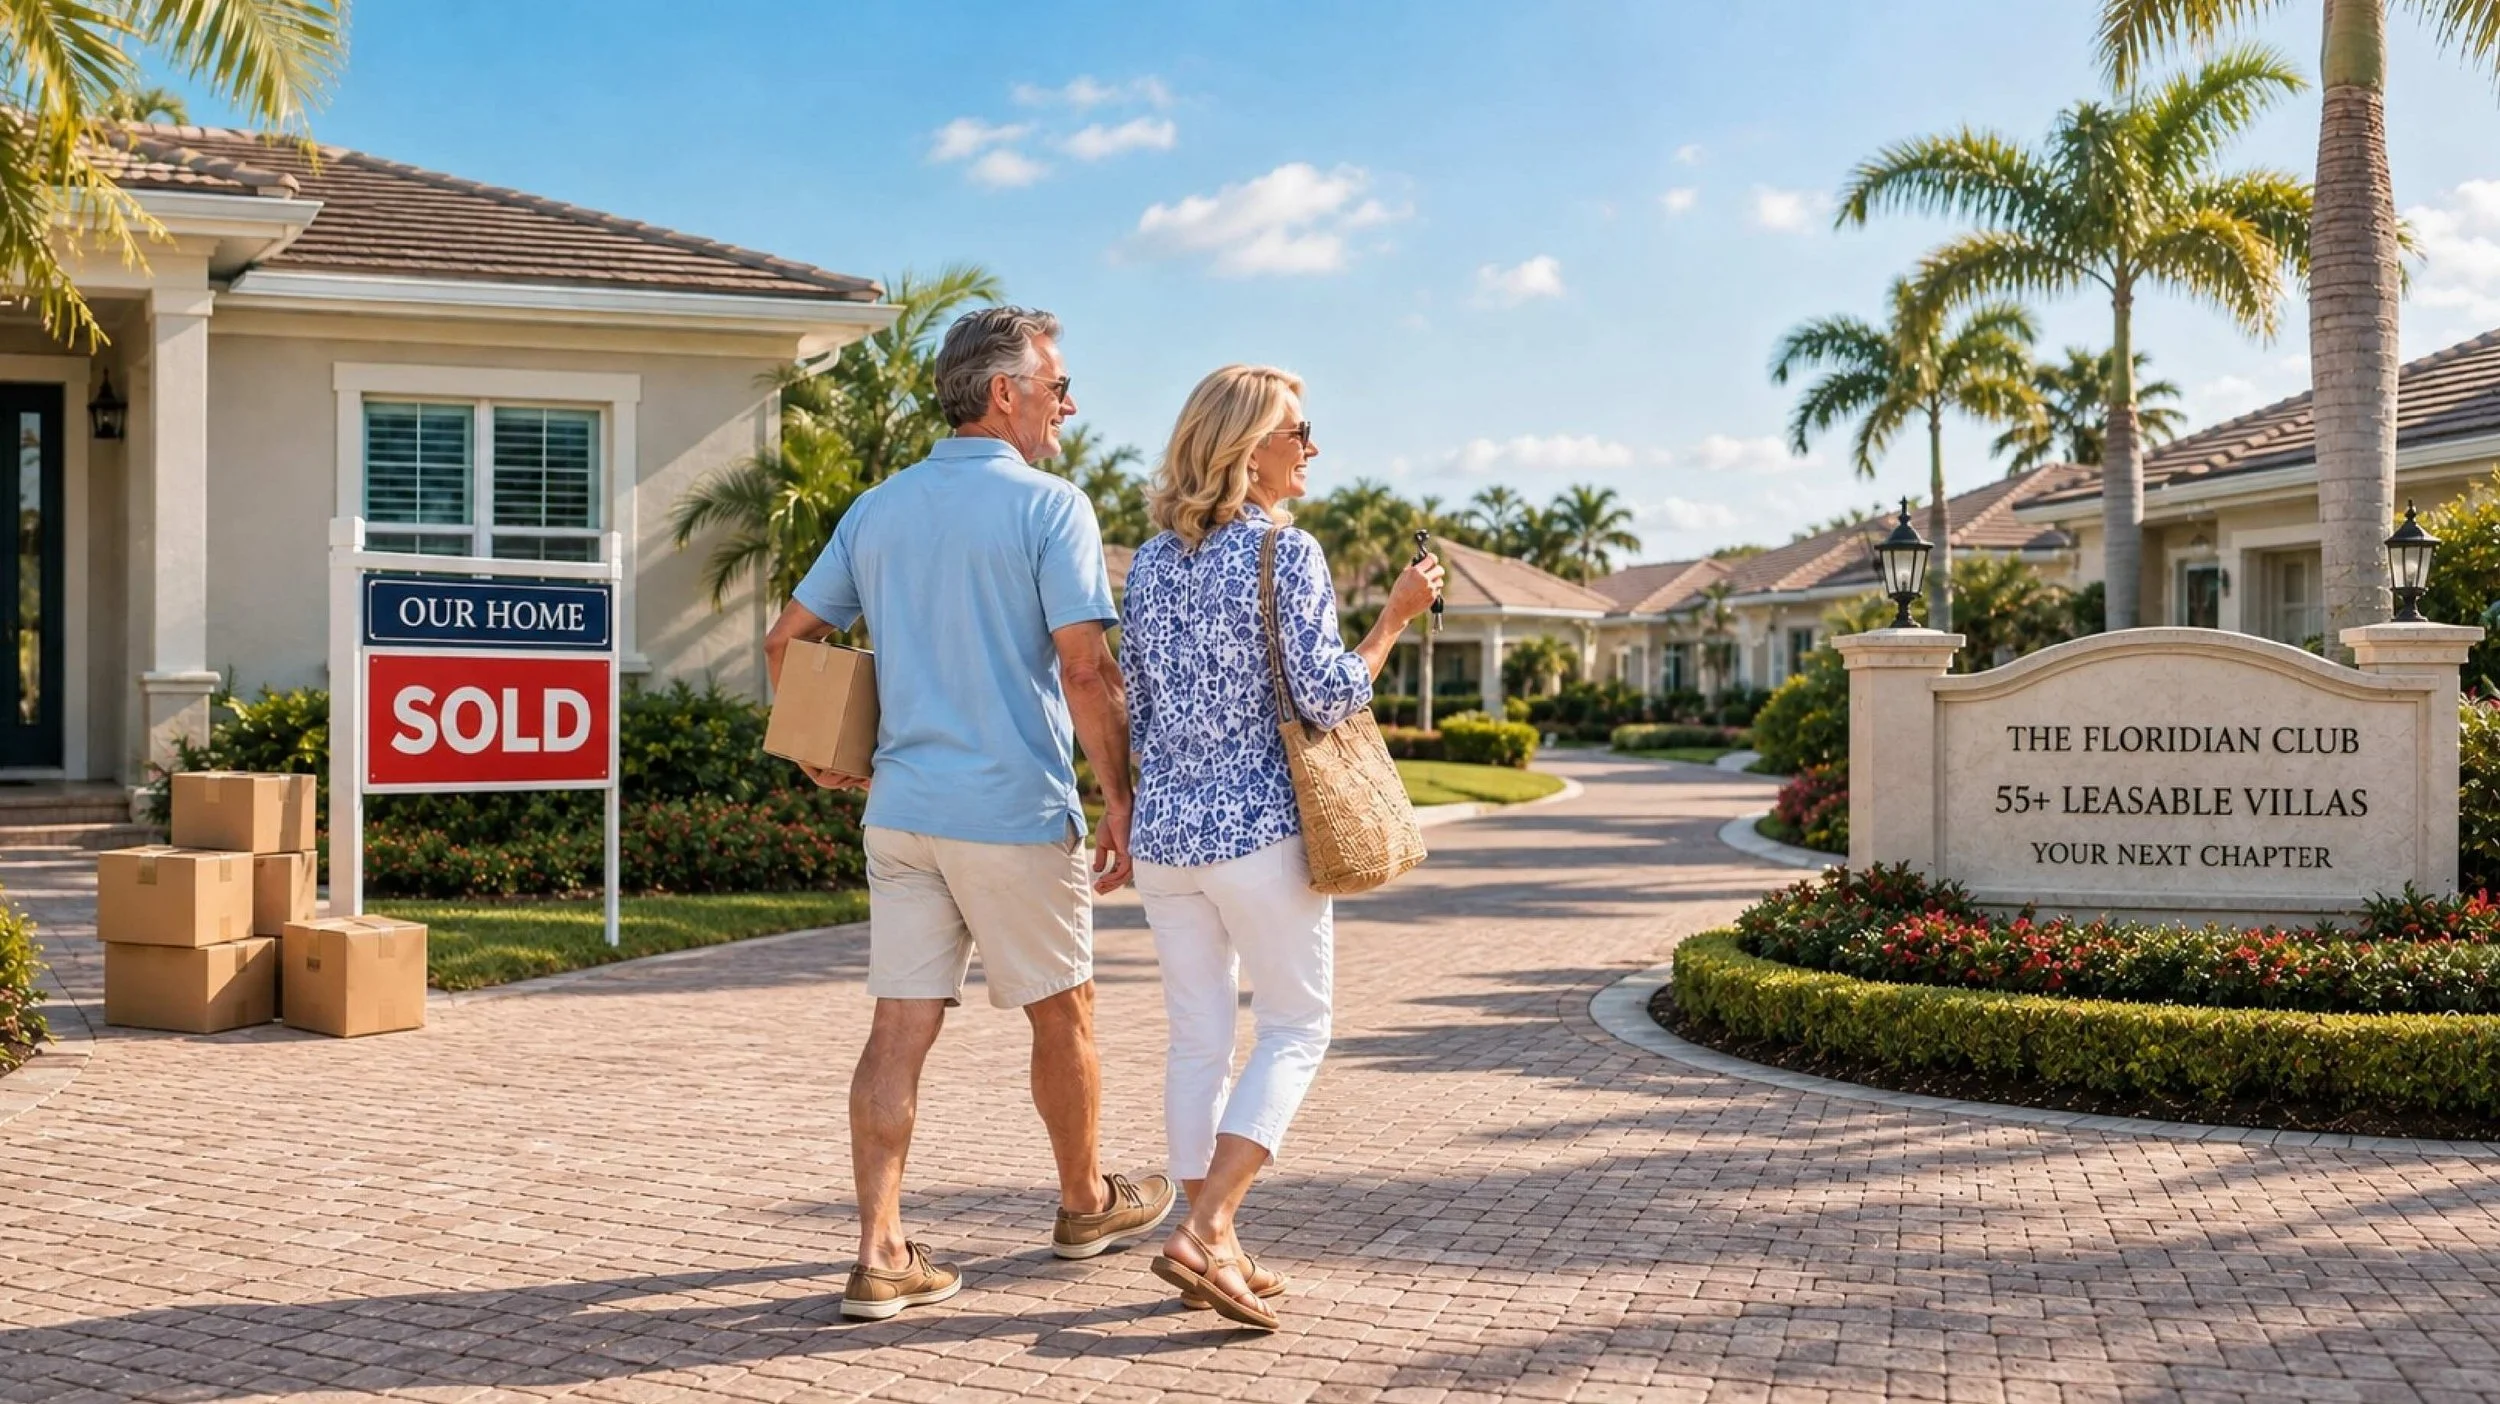
At The Floridian Club, renting is not about giving up the comforts of home. It is about enjoying a private villa or bungalow within a vibrant 55+ community while leaving many traditional ownership responsibilities behind.
Residents are not directly responsible for property-tax bills, homeowners-insurance premiums, or major ownership repairs. Interior maintenance is included according to the terms of the lease, and one-level living can make everyday life simpler and more comfortable. The Floridian Club also offers a long-term pricing commitment designed to provide greater confidence when planning for the future.*
The goal is not simply to rent a residence. It is to create more room in life—for activities, friendships, travel, relaxation, and the things that matter most.
Is selling and renting right for you?
Start by comparing the full costs and responsibilities of both choices. Consider what you are paying today, what your home may require in the future, how much equity you would receive after a sale, and what kind of lifestyle you want during your next chapter.
For some adults over 55, remaining in their current home will be the right decision. For others, selling and renting may offer something increasingly valuable:
A more predictable financial picture, fewer household responsibilities, and greater freedom to enjoy the years ahead.
Community features, pricing commitments, fees, maintenance responsibilities, and lease terms are subject to the applicable lease and current program details. This article is for general informational purposes and is not financial, investment, tax, or legal advice.